Having Medicare doesn’t mean every health care expense is covered.
That’s an important distinction—and one that can become expensive if you don’t understand it before you need care.
In fact, one of the questions the Bergen County State Health Insurance Assistance Program (SHIP) says Medicare beneficiaries frequently ask is:
“What doesn’t Medicare cover?”
It’s a good question.
Original Medicare covers a wide range of medically necessary hospital and medical services through Medicare Part A and Part B. But there are important gaps.
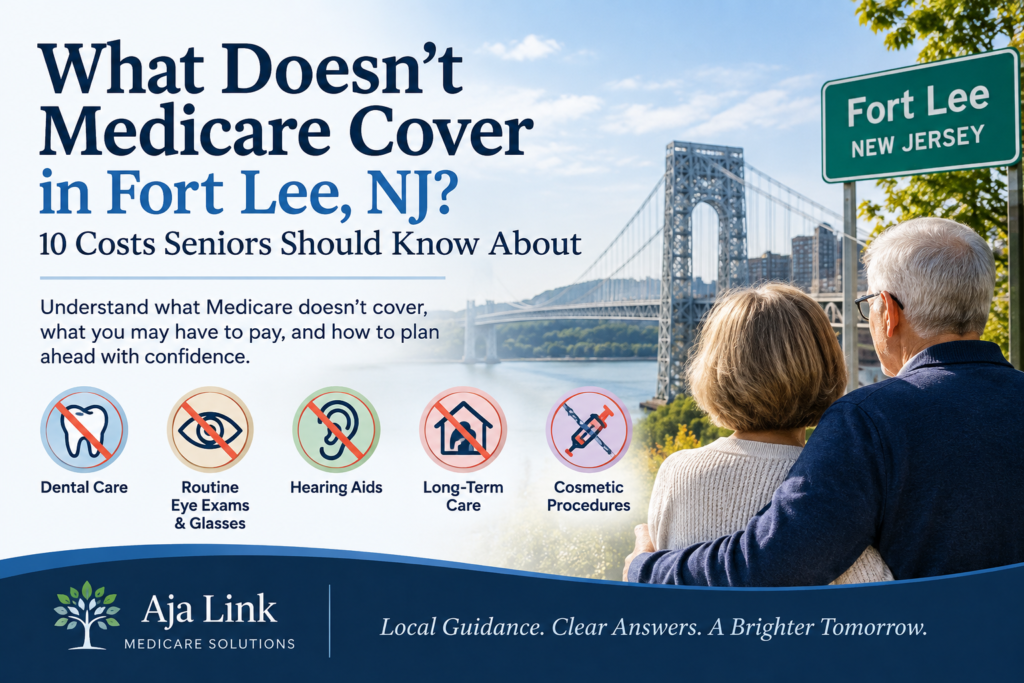
Routine dental care, most routine vision care, hearing aids and long-term custodial care are just a few examples that can surprise Medicare beneficiaries.
And there’s another important distinction:
Something being covered by Medicare doesn’t necessarily mean Medicare pays 100% of the cost.
You may still be responsible for deductibles, copayments or coinsurance for covered services.
For seniors in Fort Lee and throughout Bergen County, understanding these gaps can help you evaluate whether Original Medicare alone, Original Medicare with additional coverage, or a Medicare Advantage plan better fits your individual needs.
Here are 10 Medicare coverage gaps and potential costs you should know about.
First, Understand What “Medicare Doesn’t Cover” Really Means
Before looking at the 10 items, we need to separate two ideas that are often confused.
There are services that Original Medicare generally doesn’t cover.
Then there are services that Medicare does cover, but you may still have a portion of the cost to pay.
Those aren’t the same thing.
For example, Medicare Part B generally covers many medically necessary doctor and outpatient services. But under Original Medicare, you will typically have cost-sharing after meeting the applicable deductible.
On the other hand, routine dental cleanings generally aren’t covered by Original Medicare at all.
Understanding that difference can help you avoid assuming that your Medicare card means every health care bill is taken care of.
From My Office
When I’m helping someone understand Medicare, I don’t like to stop at:
“Is this covered?”
I also want them to ask:
“If it is covered, what could my responsibility be?”
Those two questions belong together.
A Medicare plan can provide excellent coverage and still leave you with costs you need to understand and budget for.
1. Most Routine Dental Care
This is one of the Medicare coverage gaps that surprises people most.
Original Medicare generally doesn’t cover routine dental services such as:
- Dental cleanings
- Fillings
- Routine tooth extractions
- Dentures
- Other routine dental care
There are limited situations in which Medicare may cover certain dental services when they’re closely connected to specific covered medical treatment.
But that is very different from having routine dental insurance.
What About Medicare Advantage?
Some Medicare Advantage plans offer additional dental benefits that Original Medicare doesn’t provide.
However, dental benefits can vary considerably by plan.
A plan might have limits on how much it pays, rules about which dentists you can use, copayments or restrictions on particular services.
So don’t ask only:
“Does this Medicare Advantage plan include dental?”
Ask:
“Exactly what dental services are covered, how much does the plan pay, and which dentists can I use?”
That’s a much better question.
2. Routine Eye Exams and Most Eyeglasses
Original Medicare generally doesn’t cover routine eye exams for the purpose of prescribing eyeglasses or contact lenses.
It also generally doesn’t cover ordinary eyeglasses or contact lenses.
There are exceptions.
For example, Medicare Part B can cover certain eye care related to medical conditions and covers one pair of standard-frame eyeglasses or one set of contact lenses after cataract surgery in which an intraocular lens is implanted.
But routine vision coverage is different.
Aja’s Medicare Tip
If vision is important to you, don’t compare plans based solely on whether the benefits page says “vision included.”
Find out:
- How often an eye exam is covered
- What allowance may be available for glasses or contacts
- Which providers participate
- Whether there are restrictions on frames or lenses
- How often the benefit renews
A benefit isn’t valuable simply because it appears on a brochure.
It has to be useful for you.
3. Hearing Aids and Routine Hearing-Aid Exams
Original Medicare doesn’t generally cover hearing aids or exams specifically for fitting hearing aids.
For someone who eventually needs hearing aids, that can represent a meaningful out-of-pocket expense.
Medicare may cover certain diagnostic hearing and balance exams when Medicare’s requirements are met, but that should not be confused with routine hearing-aid coverage.
Some Medicare Advantage plans offer additional hearing benefits.
Again, the details matter.
Coverage may vary based on the plan, hearing-aid models, participating providers, frequency and the amount the plan contributes.
From My Office
Dental, vision and hearing benefits can make a Medicare Advantage plan look very attractive.
And they can certainly be valuable.
But I don’t recommend choosing your entire Medicare health plan based on one extra benefit.
Your doctors, hospitals, prescriptions and overall medical costs should come first.
Then we look at the extra benefits.
4. Long-Term Custodial Care
This may be the most financially important Medicare coverage gap on this list.
Medicare generally does not pay for long-term custodial care.
Custodial care can include help with everyday activities such as:
- Bathing
- Dressing
- Using the bathroom
- Eating
- Other ongoing personal-care needs
That care may be provided at home, in the community, in assisted living or in a nursing home.
This is different from qualifying short-term skilled nursing facility care, which Medicare Part A may cover when Medicare’s requirements are met.
The words “nursing home” can therefore create confusion.
Someone may hear that Medicare covers skilled nursing facility care and assume Medicare will pay indefinitely for long-term nursing-home care.
It generally does not.
Medicare specifically distinguishes skilled medical care from long-term custodial care.
Why Fort Lee Families Should Understand This Before a Crisis
Long-term care isn’t only an issue for the person receiving care.
It can become a major issue for spouses and adult children who suddenly find themselves trying to understand care options, costs and public benefits while also dealing with a health crisis.
Bergen County’s Division of Senior Services provides resources for older adults and caregivers, including information about aging in place and long-term-care options.
This subject deserves much more than a few paragraphs—which is why our next Fort Lee article will focus specifically on Medicare, nursing homes and long-term care.
5. Prescription Drugs Aren’t Automatically Included With Original Medicare
Original Medicare Part A and Part B don’t provide the same outpatient prescription drug coverage as Medicare Part D.
If you choose Original Medicare and want Medicare prescription drug coverage, you can generally enroll in a separate Part D plan.
Most Medicare Advantage plans include Part D prescription drug coverage, although plan designs and formularies vary.
This is an area where people sometimes make a costly assumption.
They think:
“I have Medicare, so my prescriptions are covered.”
Not necessarily.
You need to understand how you’re getting your prescription drug coverage.
And even when you have Part D, the particular plan matters because formularies, drug tiers, pharmacies and coverage rules can affect your costs.
Aja’s Medicare Tip
Don’t wait until you’re standing at the pharmacy counter to understand your prescription coverage.
Before choosing Medicare coverage, make a list of:
- Your medications
- Exact dosages
- How frequently you take them
- Your preferred pharmacy
Then compare the actual drug coverage.
The lowest-premium plan isn’t automatically the plan that will cost you the least.
6. Routine Physical Exams Are Not the Same as Medicare Wellness Visits
This is another area where Medicare terminology can cause confusion.
Medicare Part B covers a yearly Wellness visit, but a Medicare Wellness visit is not the same thing as a traditional routine physical exam.
The yearly Wellness visit is designed primarily to help you and your health care provider develop or update a personalized prevention plan based on your health and risk factors.
It may include things such as reviewing your medical and family history, medications, measurements, screenings, risk factors and preventive-care needs.
But Original Medicare generally does not cover a routine physical exam simply because you want a comprehensive physical.
“Welcome to Medicare” Is Different Too
During your first 12 months of having Medicare Part B, Medicare covers a one-time “Welcome to Medicare” preventive visit.
After you’ve had Part B for more than 12 months, you’re generally eligible for a yearly Wellness visit.
Neither should automatically be assumed to be the same as a traditional annual physical.
Aja’s Medicare Tip
When making an appointment, be specific about what you’re scheduling.
Ask the doctor’s office:
“Am I scheduling my Medicare yearly Wellness visit, or am I scheduling a routine physical?”
Those words can matter.
And if additional tests or services are performed during a preventive visit that aren’t included in the preventive benefit, you may have cost-sharing for those additional services.
7. Most Health Care Outside the United States
Original Medicare generally doesn’t cover health care you receive outside the United States, although there are a few limited exceptions.
That’s particularly important for Medicare beneficiaries who travel internationally or spend significant time outside the country.
Some Medigap policies can provide limited foreign-travel emergency benefits, subject to the policy’s rules and limits.
Some Medicare Advantage plans may also provide coverage for emergency or urgently needed care while traveling outside the United States.
But benefits vary.
If You Travel, Ask Before You Go
Don’t assume that because you have Medicare, you’ll have the same coverage everywhere in the world.
Before traveling internationally, find out:
- Whether your coverage includes foreign emergency care
- What constitutes an emergency
- What your cost-sharing may be
- Whether there are coverage limits
- Whether you may need to pay first and request reimbursement
- What documentation you should keep
This is especially important if international travel is part of your retirement plans.
8. Care From Providers Who Opt Out of Medicare
Having Original Medicare generally gives you broad access to doctors and hospitals throughout the United States that participate in Medicare.
But that doesn’t mean every doctor in the country must accept Medicare.
Some doctors and other practitioners may formally opt out of Medicare.
If you receive services from a provider who has opted out, Medicare generally won’t pay for those services except in certain emergency or urgent-care circumstances.
You and the provider may instead enter into a private contract under Medicare’s rules.
Don’t Assume—Verify
If you’re seeing a new specialist, especially for an expensive service, verify how that provider works with Medicare.
This becomes particularly important when you’re comparing Original Medicare with Medicare Advantage.
With Medicare Advantage, you also need to understand the plan’s provider network and out-of-network rules.
From My Office
I tell people that the question isn’t simply:
“Does my doctor take Medicare?”
If you’re considering Medicare Advantage, the question becomes:
“Does my doctor participate in this specific Medicare Advantage plan and network?”
Those are not the same question.
For Fort Lee residents who may receive care from doctors and specialists throughout Bergen County or elsewhere in northern New Jersey and the New York metropolitan area, provider access can be an especially important part of comparing coverage.
9. Original Medicare Does Not Have an Annual Out-of-Pocket Maximum
This is one of the most important financial differences to understand about Original Medicare.
Original Medicare by itself does not have a yearly limit on what you may have to pay out of pocket for covered Part A and Part B services.
For many Part B-covered services, for example, you generally pay 20% of the Medicare-approved amount after meeting the applicable Part B deductible.
Depending on the care you need, those costs can add up.
This is one reason people with Original Medicare sometimes consider additional coverage such as a Medicare Supplement Insurance policy, also known as Medigap.
How Is Medicare Advantage Different?
Medicare Advantage plans are required to have an annual limit on what you pay out of pocket for covered Part A and Part B services.
The specific maximum and how costs work can vary by plan.
Once you reach the plan’s applicable annual limit, you generally pay nothing for covered Part A and Part B services for the remainder of the year.
That doesn’t mean Medicare Advantage is automatically better than Original Medicare with Medigap.
It means the two approaches handle your health care costs differently.
Look at Risk, Not Just Premium
This is why I don’t like Medicare comparisons that focus only on:
“How much is the monthly premium?”
Your monthly premium is only one number.
You also need to understand:
- Deductibles
- Doctor copays
- Specialist copays
- Hospital costs
- Outpatient surgery costs
- Diagnostic testing and imaging
- Coinsurance
- Prescription costs
- Your potential annual out-of-pocket exposure
A plan with an attractive premium may still expose you to significant costs when you actually use health care.
10. Some Services You May Consider “Health Care” Still Aren’t Covered
This final category is important because people sometimes assume that if a service helps their health, Medicare must pay for it.
That’s not necessarily how Medicare coverage works.
Depending on the circumstances, Original Medicare generally doesn’t cover certain services such as:
- Routine foot care in many situations
- Cosmetic surgery when performed solely for cosmetic purposes
- Routine dental care
- Hearing aids
- Routine eye exams for eyeglasses
- Long-term custodial care
But there can be important exceptions.
For example, Medicare may cover certain foot care when medically necessary because of particular medical conditions.
Medicare may also cover reconstructive surgery when Medicare’s medical-necessity requirements are met, even though purely cosmetic surgery generally isn’t covered.
That’s why broad statements like “Medicare doesn’t cover foot care” can be misleading.
The reason you’re receiving the service can matter.
Medical Necessity Matters
When you’re unsure whether Medicare covers a particular service, don’t rely on what happened to a friend or neighbor.
Ask:
“Does Medicare cover this service for my medical situation, and what requirements have to be met?”
That is much more useful.
The Bigger Issue: Medicare Coverage Gaps Can Work Very Differently Depending on How You Get Medicare
Now we’ve reached the most important point of this article.
Knowing what Original Medicare doesn’t cover is useful.
But the next question should be:
“What can I do about those gaps?”
There isn’t one answer for everybody.
Some people choose Original Medicare with a Medigap policy and separate Part D prescription drug coverage.
Others choose a Medicare Advantage plan, which replaces Original Medicare as the way they receive their Part A and Part B benefits and often includes Part D coverage and additional benefits.
Those choices can create very different combinations of:
- Monthly premiums
- Provider access
- Prescription coverage
- Dental, vision and hearing benefits
- Copayments and coinsurance
- Network requirements
- Travel flexibility
- Out-of-pocket protection
Quick Comparison
Original Medicare alone: Broad access to Medicare-participating providers, but significant coverage gaps and no annual Part A/Part B out-of-pocket maximum.
Original Medicare + Medigap + Part D: Can help make certain Original Medicare costs more predictable and provide prescription coverage, but generally involves additional monthly premiums. Routine dental, vision and hearing coverage may still need to be addressed separately.
Medicare Advantage: Provides Part A and Part B benefits through a private Medicare-approved plan, usually includes Part D, has an annual medical out-of-pocket limit, and may include extra benefits such as dental, vision and hearing. Provider networks, prior authorization and plan-specific rules can apply.
From My Office
This is why I don’t believe the Medicare conversation should begin with:
“Which company has the best plan?”
It should begin with:
“What do you need from your Medicare coverage?”
I want to know about your doctors.
Your specialists.
Your prescriptions.
The hospitals you prefer.
Your budget.
How frequently you travel.
And which potential out-of-pocket costs concern you most.
Only then does it make sense to start comparing coverage.
Medicare isn’t one-size-fits-all, and neither are the gaps Medicare leaves behind.
How Can Fort Lee Seniors Prepare for Medicare’s Coverage Gaps?
Learning what Medicare doesn’t cover isn’t meant to scare you.
It’s meant to help you plan.
You don’t necessarily need insurance for every possible expense, and a Medicare Advantage plan isn’t automatically better simply because it offers additional benefits.
Likewise, Original Medicare with Medigap isn’t automatically the right choice for everyone.
The goal is to understand where your coverage begins, where it ends, and what you could be responsible for paying.
Start With Your Own Health Care Needs
Before comparing Medicare coverage, make a simple list of what matters most to you.
Include:
- Your primary care doctor
- Specialists you currently see
- Hospitals you prefer
- Prescription medications and dosages
- Preferred pharmacy
- Dental, vision, and hearing needs
- Expected travel
- Your monthly budget
- How comfortable you are with copayments and other out-of-pocket costs
That list is much more useful than starting with an insurance company brochure.
From My Office
One thing I want people to know about working with me is that I don’t believe every Medicare beneficiary should be given the same answer.
My job isn’t to convince everyone that Medicare Advantage is best.
It isn’t to convince everyone that Medigap is best either.
My job is to help you understand the differences, look carefully at the options available to you, and make an informed decision based on your situation.
Sometimes an extra benefit looks attractive, but the medical side of the plan isn’t the right fit.
Sometimes a plan with a higher monthly cost provides features a particular person values.
And sometimes the coverage someone already has continues to work well for them.
Good Medicare guidance should help you understand your choices—not pressure you into changing coverage.
5 Medicare Coverage Mistakes I Want Fort Lee Seniors to Avoid
Understanding Medicare’s gaps is important. Knowing how people get caught by them is even more useful.
Mistake #1: Assuming “Medicare Covers It” Means You Pay Nothing
A service can be covered by Medicare and still have a deductible, copayment, or coinsurance.
Always distinguish between covered and covered at no cost to you.
They are not the same thing.
Mistake #2: Choosing a Medicare Advantage Plan for One Extra Benefit
Dental, vision, hearing, and other supplemental benefits can be valuable.
But don’t let a dental allowance or another attractive extra benefit distract you from checking your doctors, hospitals, prescriptions, medical copays, out-of-pocket limit, and plan rules.
Extra benefits should be part of the comparison—not the entire comparison.
Mistake #3: Assuming Medigap Fills Every Medicare Gap
The word “supplement” sometimes causes people to assume a Medigap policy covers everything Original Medicare doesn’t.
It doesn’t.
Medigap is primarily designed to help with certain out-of-pocket costs for services covered by Original Medicare.
Medigap policies generally don’t cover long-term care, routine dental or vision care, hearing aids, or private-duty nursing. Policies sold after 2005 don’t include prescription drug coverage.
That’s why someone choosing Original Medicare with Medigap may also consider separate Part D prescription drug coverage and how they’ll handle services Medicare and Medigap generally don’t cover.
Mistake #4: Assuming Medicare Will Pay for Long-Term Nursing Home Care
This misunderstanding can have serious financial consequences.
Medicare doesn’t pay for long-term custodial care.
That includes much of the ongoing assistance people may eventually need with activities such as bathing, dressing, eating, and using the bathroom.
That is different from Medicare-covered skilled nursing facility care when Medicare’s eligibility requirements are met.
If you’re helping an aging parent, this is a distinction worth understanding before your family is facing an urgent care decision.
Aja’s Medicare Tip
When someone tells you that “Medicare covers nursing homes,” ask what type of care they’re talking about.
Short-term skilled nursing facility care and long-term custodial care are not the same thing.
That distinction can have major financial consequences for a family.
Mistake #5: Taking Someone Else’s Medicare Advice as Your Answer
Your neighbor may love their Medicare plan.
Your sibling may tell you exactly what they chose.
A television commercial may make one benefit sound incredible.
None of those things tells you whether that coverage fits your doctors, prescriptions, finances, and health care preferences.
Medicare decisions are personal.
Use other people’s experiences as information—not as a substitute for evaluating your own situation.
A Simple Medicare Coverage Checklist
Before enrolling in or changing Medicare coverage, I recommend being able to answer these questions:
- Are my doctors and specialists accessible under the coverage I’m considering?
- What hospitals and facilities can I use?
- How will my prescriptions be covered?
- What will I pay monthly?
- What could I pay when I actually use medical services?
- Is there an annual out-of-pocket limit for my medical coverage?
- What dental, vision, or hearing benefits are actually included?
- What important services are not covered?
- How will my coverage work when I travel?
- Am I comfortable with the rules, networks, and potential costs of this coverage?
If you can’t answer one of these questions, that doesn’t mean the coverage is bad.
It means you have one more question to ask before making your decision.
Frequently Asked Questions About What Medicare Doesn’t Cover
Does Original Medicare Cover Dental Care?
Original Medicare generally doesn’t cover routine dental care such as cleanings, fillings, routine tooth extractions, dentures, and dental implants.
However, Medicare may cover certain dental services when they are directly related to specific Medicare-covered medical treatments or when other Medicare coverage requirements are met.
This is why saying simply “Medicare never covers dental” would be inaccurate.
Does Medicare Cover Routine Eye Exams and Glasses?
Original Medicare generally doesn’t cover routine eye exams for eyeglasses or contact lenses.
Medicare does cover certain medically necessary eye services and has specific coverage for corrective lenses following qualifying cataract surgery.
Some Medicare Advantage plans offer additional routine vision benefits.
Does Medicare Cover Hearing Aids?
Original Medicare doesn’t cover hearing aids or exams specifically for fitting hearing aids.
Some Medicare Advantage plans offer additional hearing benefits.
Always review the details because hearing benefits can differ among plans.
Does Medicare Pay for Long-Term Care in a Nursing Home?
Medicare does not pay for long-term custodial care simply because that care is provided in a nursing home.
Medicare Part A can cover qualifying skilled nursing facility care when Medicare’s requirements are met, but skilled nursing care and long-term custodial care are different types of care.
This distinction is important enough that we’ll explore it in much greater detail in a separate Fort Lee guide to Medicare, nursing homes, and long-term care.
Does Medicare Cover an Annual Physical?
Original Medicare doesn’t cover a routine physical exam in the traditional sense.
Medicare Part B does cover a yearly Wellness visit for eligible beneficiaries.
The Wellness visit is designed to develop or update a personalized prevention plan and is not the same as a routine physical.
Does Medicare Advantage Cover Things Original Medicare Doesn’t?
Medicare Advantage plans must cover the medically necessary services that Original Medicare covers, and many plans offer additional benefits that Original Medicare doesn’t cover, such as certain dental, vision, and hearing services.
However, benefits, costs, provider networks, and plan rules vary.
Never assume that every Medicare Advantage plan offers the same extra benefits.
If I Have Medigap, Does It Cover Long-Term Care?
Generally, no.
Medigap policies generally don’t cover long-term custodial care. They are primarily designed to help pay certain out-of-pocket costs associated with Original Medicare.
Medicare Help and Senior Resources in Fort Lee and Bergen County
You don’t have to figure out every Medicare question alone.
Fort Lee’s Richard & Catherine Nest Adult Activity Center provides programs and resources for older residents, while the Borough of Fort Lee also provides senior and human services for the community.
Bergen County operates its State Health Insurance Assistance Program (SHIP), which provides free and confidential Medicare counseling.
In fact, Bergen County SHIP identifies questions such as what Medicare doesn’t cover, patient responsibility, Medigap versus HMO coverage, long-term care, and prescription drug plans among the Medicare questions it frequently receives.
These are valuable resources, particularly for people who want independent Medicare education or assistance with Medicare-related issues.
From My Office
I believe trustworthy Medicare guidance includes telling people where they can get help even when that help doesn’t come from me.
SHIP, Medicare.gov, and local senior-service organizations can all be useful resources.
If you work with an insurance agent, that person should add another layer of help by taking the time to understand your individual situation and clearly explaining the coverage options available to you.
You should feel comfortable asking questions.
And you should never feel rushed into making a Medicare decision you don’t understand.
Final Thoughts: Know What Medicare Covers Before You Need to Use It
Medicare provides important health coverage to millions of Americans.
But Medicare was never designed to pay for every health-related expense.
The time to learn about those gaps isn’t after you receive an unexpected bill.
It’s before you choose your coverage.
Understand what’s covered.
Understand what’s not.
Know what you may have to pay.
Check your doctors.
Review your prescriptions.
Think about the health care services you’re most likely to use.
And don’t be afraid to ask questions when something isn’t clear.
Most importantly, don’t choose Medicare coverage simply because someone tells you a particular plan is “the best.”
The better question is whether the coverage is right for you.
About the Author
Aja Link is a licensed Medicare insurance agent serving Medicare beneficiaries in New York and New Jersey.
Aja’s approach to Medicare is centered on education first.
She believes people deserve to understand not only the benefits of a Medicare option, but also its limitations, costs, rules, and tradeoffs before making a decision.
Rather than beginning with an insurance company or a particular plan, Aja starts with the person: their doctors, specialists, prescriptions, preferred hospitals, budget, travel habits, and health care priorities.
She does not believe Medicare Advantage is automatically right for everyone, nor does she believe Medigap is automatically right for everyone.
Her goal is to explain the differences in plain English, answer questions honestly, and help Medicare beneficiaries evaluate the options available to them without unnecessary pressure.
For Aja, earning someone’s trust is more important than simply making an enrollment.
Have a Medicare question or want help understanding your options?
Aja Link
Licensed Medicare Insurance Agent
New York & New Jersey
Phone: 516-313-8918
Email: ajaglink@gmail.com
There is no obligation to enroll when requesting information.
References
Medicare.gov — What’s Not Covered by Original Medicare
Medicare.gov — Medicare Supplement Insurance (Medigap) Coverage
Medicare.gov — Dental Services
Medicare.gov — Yearly Wellness Visits
Bergen County Division of Senior Services — SHIP Medicare Counseling
Borough of Fort Lee — Senior & Human Services
Medicare Disclaimer
This article is for educational purposes only and is not intended to provide legal, medical, financial, or tax advice.
Medicare coverage rules, costs, and benefits can change. Medicare Advantage and Medicare Part D plan availability, premiums, benefits, provider networks, formularies, copayments, coinsurance, and other plan details vary by plan and service area and may change from year to year.
Medigap availability, premiums, and eligibility can also depend on individual circumstances and applicable federal and state protections.
Always review current Medicare information and official plan documents before enrolling in or changing Medicare coverage.
Not connected with or endorsed by the U.S. government or the federal Medicare program.