If you have Medicare, one of the most important things you can do before 2027 is not assume that the coverage you have today will work exactly the same way next year.
Your Medicare Advantage or Part D plan may have worked very well for you in 2026. That doesn’t automatically mean you need to change it.
But it also doesn’t mean you should simply ignore the Annual Enrollment Period and let your coverage renew without reviewing it.
Plans can change from one year to the next. Premiums, copayments, prescription drug coverage, provider networks and benefits can all affect what you pay and how you receive care.
Your situation can change, too.
Maybe you started a new medication. Maybe you’re seeing a new specialist. Maybe you’re planning a procedure. Maybe your preferred pharmacy changed. Or perhaps you’re simply trying to keep your healthcare expenses under better control.
That’s why I believe the 2027 Medicare Annual Enrollment Period (AEP) should be treated as an annual Medicare checkup.
And you don’t have to research all of this by yourself.
As a licensed Medicare agent, one of the most important things I do during AEP is help clients review these details, research their options and understand what changed before they make a decision.
When Is the 2027 Medicare Annual Enrollment Period?
The Medicare Annual Enrollment Period runs:
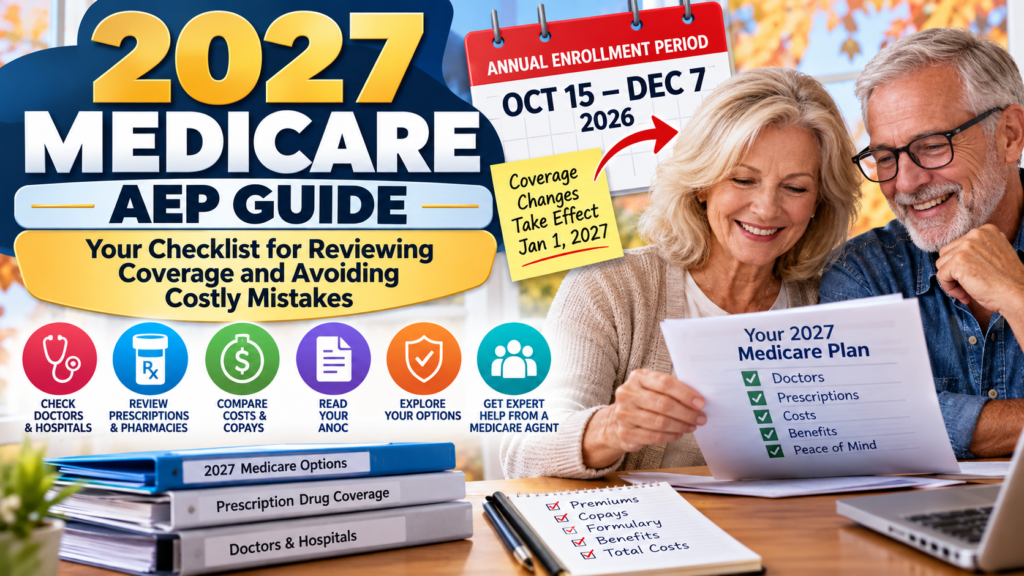
October 15 through December 7, 2026
Changes made during this period generally take effect January 1, 2027.
During AEP, people with Medicare can review their existing coverage and, depending on their situation, make changes involving Medicare Advantage and Medicare Part D coverage.
But here’s something important:
AEP isn’t only for people who want to change plans.
It’s also an opportunity to verify that the coverage you already have still makes sense for the coming year.
If the research shows that your current plan continues to fit your needs, staying with it may make sense.
The important part is that you’ve checked instead of assumed.
Your 2027 Medicare AEP Checklist
This is the checklist I want Medicare beneficiaries to work through before deciding what to do for 2027.
| ✓ | Review This for 2027 | Why It Matters |
|---|---|---|
| 📬 | Read your ANOC | Your Annual Notice of Change explains important changes taking effect in January. |
| 🚨 | Confirm your plan for 2027 | Don’t assume everything about your current coverage will remain the same. |
| 💵 | Check your premium | Compare what you’ll actually pay in 2027 with what you paid in 2026. |
| 🩺 | Review medical copays | Look beyond the premium at specialists, hospitals, outpatient care and other services you may use. |
| 💰 | Check your maximum out-of-pocket | This can be an important part of your potential annual medical costs in Medicare Advantage. |
| 👩⚕️ | Verify doctors and specialists | Check the providers that matter to you for the new plan year. |
| 🏥 | Check hospitals | Make sure the hospitals and health systems you prefer fit your 2027 coverage. |
| 💊 | Run your prescriptions | Check the formulary, drug tier, restrictions and estimated costs. |
| 🏪 | Review pharmacies | Pharmacy network and preferred pharmacy status can affect prescription costs. |
| 📋 | Check coverage rules | Look for prior authorization, step therapy and quantity limits when applicable. |
| 🦷 | Review extra benefits | Dental, vision, hearing, OTC and other benefits can change and shouldn’t be reviewed in isolation. |
| 🔎 | Compare your options | Find out whether your existing coverage still fits before deciding to stay or change. |
Medicare specifically recommends checking whether a plan covers your prescriptions, whether doctors and pharmacies participate, and what you’ll pay in premiums, deductibles and estimated prescription costs.
Start With Your Annual Notice of Change — Don’t Throw It Away
One of the most important documents you’ll receive before AEP is your Annual Notice of Change, commonly called the ANOC.
Your plan sends this document each fall. Medicare says the ANOC identifies changes in your plan’s coverage, costs and other details that will become effective in January.
Please don’t assume it’s just another piece of Medicare mail.
Read it.
Compare the new information with the coverage you’ve been using this year.
Look for changes involving your premium, deductibles, copayments, prescription coverage and benefits.
And if something isn’t clear, ask.
From My Office: Bring Me Your ANOC
When I’m helping someone prepare for AEP, the question isn’t simply:
“Do you like your current plan?”
You may love your current plan.
What I want to know is:
Will you still like it after we see what it looks like in 2027?
Bring me your ANOC. Bring me your prescription list. Tell me which doctors and specialists you’re seeing and which hospitals matter to you.
Then we can research the coverage rather than guess.
My job isn’t to move someone from one plan to another just because AEP arrived.
My job is to help you understand what you have, what changed and what your options look like for the coming year so you can make an informed decision.
One of the biggest Medicare mistakes I see is focusing too heavily on the monthly premium.
The premium matters.
But it is only one piece of the financial picture.
For Medicare Advantage coverage, you may also need to consider specialist copays, hospital costs, outpatient procedures, diagnostic services and the plan’s annual maximum out-of-pocket amount.
For prescription coverage, you need to consider the drugs you actually take, not simply the Part D premium.
CMS is projecting relatively stable Medicare Advantage and Part D premiums nationally for 2027, but national averages don’t tell you what your particular plan and healthcare needs will cost. CMS is specifically encouraging beneficiaries to review their current coverage and compare 2027 options because plan costs and benefits can change from year to year.
A plan with a very low premium isn’t automatically your least expensive option.
And a plan with a higher premium isn’t automatically a bad option.
The better question is: What could this coverage realistically cost you based on the healthcare and prescriptions you actually use?
Your Doctors and Hospitals Should Be One of the First Things You Check
A Medicare Advantage plan can have attractive benefits and a low monthly premium, but those features may not mean much if the doctors and hospitals you rely on don’t participate in the plan.
Medicare Advantage plans may use provider networks, and depending on the type of plan, receiving non-emergency care outside the network may cost more or may not be covered.
Before choosing your 2027 coverage, I recommend checking your:
Primary care doctor, specialists, hospitals, outpatient facilities and other important healthcare providers.
Don’t assume that because a doctor accepted your plan in 2026, everything will automatically be the same in 2027.
From My Office: I Want the Actual Names
When I review coverage with a client, I don’t want to hear only:
“My doctors take Medicare.”
I want the names.
Which cardiologist? Which orthopedic doctor? Which hospital? Which specialists are important to you?
Then we can research the specific plan.
That’s one of the advantages of working with a Medicare agent. Instead of trying to sort through multiple plans, networks, formularies and benefit documents on your own, you can have someone help organize and research the information with you.
Your Prescription List Can Completely Change the Comparison
This is an area where I believe people can make financially costly mistakes.
Every Medicare drug plan has a formulary, which is the plan’s list of covered prescription drugs. Formularies can differ between plans. Plans also place drugs into tiers, and those tiers can affect what you pay.
So don’t compare Part D coverage—or a Medicare Advantage plan that includes Part D—without entering your actual prescriptions.
For every medication, I want to look at:
Is it covered? What tier is it on? What could it cost? Does it require prior authorization? Is there step therapy? Is there a quantity limit?
Medicare confirms that drug plans can use prior authorization, step therapy and quantity limits.
Don’t Forget the Pharmacy
Two people taking the same prescription with the same Medicare plan could potentially have different costs depending on where they fill it.
Some plans have preferred in-network pharmacies, which may offer lower out-of-pocket costs than other pharmacies in the network. Using an out-of-network pharmacy can result in substantially different costs and, depending on the circumstances, you may have to pay the full cost.
That’s why I want to know which pharmacy you actually use, not simply which medications you take.
Know the Important 2027 Part D Numbers
There are two major Part D figures beneficiaries should know for 2027.
| 💊 2027 Part D Figure | Amount | What It Means |
|---|---|---|
| Maximum standard deductible | $700 | The defined standard Part D deductible for 2027. Individual plan designs can vary. |
| Annual out-of-pocket threshold | $2,400 | Once qualifying out-of-pocket spending on covered Part D drugs reaches this amount, the beneficiary enters catastrophic coverage. |
CMS finalized both amounts for 2027. The standard deductible increased from $615 in 2026 to $700 in 2027, while the annual Part D out-of-pocket threshold increased from $2,100 to $2,400.
You may also hear that the 2027 national base beneficiary premium is $41.33.
That does not mean everyone will pay $41.33 for Part D.
The national base beneficiary premium is part of the formula used to calculate plan-specific basic premiums. Actual premiums vary by plan and can also be affected by other factors.
This is another reason I don’t want clients choosing prescription coverage based on one number.
We need to run the medications.
A $0-premium Medicare Advantage plan can be appropriate for some people.
But $0 premium does not mean $0 healthcare costs.
Depending on the plan and services you use, you may have copayments or coinsurance for specialists, hospital care, outpatient procedures, diagnostic testing and other covered services.
You should also review the plan’s maximum out-of-pocket amount for covered Part A and Part B services.
Think about the difference between these two questions:
“How much is my monthly premium?”
and
“What could my healthcare realistically cost me during the year?”
Those aren’t the same question.
A Simple Way to Review the Financial Picture
| 💰 Don’t Check Only This | 🔎 Also Research This |
|---|---|
| Monthly premium | Medical copays and coinsurance |
| $0 premium | Maximum out-of-pocket |
| Dental allowance | Your medical provider network |
| OTC benefit | Hospital participation |
| Drug plan premium | Your actual prescriptions |
| Prescription copay shown in an ad | Formulary, tier and pharmacy |
| Extra benefits | The medical coverage underneath them |
Extra benefits can certainly be valuable.
But I don’t want someone choosing coverage primarily because one plan offers a larger dental benefit, OTC allowance or another attractive extra while overlooking a doctor, hospital, prescription or potentially significant medical cost.
What Changed From 2026 to 2027?
This is one of the most important questions I ask during an annual review.
Don’t just ask:
“What does this plan cover?”
Ask:
“What changed?”
Compare the 2027 information with what you had in 2026.
Look at your premium. Look at specialist and hospital copays. Look at your maximum out-of-pocket. Check your prescriptions. Check the pharmacy. Review your benefits.
And then compare those changes with your own changes.
Maybe you take a medication today that you didn’t take last AEP.
Maybe you now see three specialists instead of one.
Maybe you’re expecting surgery.
Maybe you’re traveling more.
Your Medicare coverage should be reviewed based on the person you are today, not the healthcare needs you had several years ago.
Why I Believe an Annual Review With an Agent Can Be So Valuable
Medicare itself lists a trusted agent or broker as one resource beneficiaries can use when comparing Medicare coverage. Medicare recommends checking prescriptions, provider and pharmacy networks, premiums, deductibles and estimated annual prescription costs when evaluating a plan.
That’s a lot of information to research.
And that’s exactly where I believe I provide value.
From My Office: Let Me Do the Research With You
My clients don’t need to become Medicare experts every October.
That’s my job.
Give me your doctors.
Give me your specialists.
Give me your prescriptions and preferred pharmacy.
Tell me which hospitals you want access to and what’s important to you financially.
Then I can help research the available plans, compare the details and explain what I’m finding in plain language.
Sometimes that research leads to a different plan.
Sometimes it confirms that the plan you already have is still a good fit.
Either outcome is valuable because the decision was based on research rather than assumption.
My goal isn’t to change your coverage simply because it’s AEP.
My goal is to help you avoid overlooking something that could affect your healthcare—or your wallet—in 2027.
What Happens If You Do Nothing During AEP?
This is a question I hear frequently.
If your current Medicare Advantage or Part D plan will continue to be offered in 2027 and you’re satisfied that the coverage will still meet your needs, you generally don’t have to make a change during AEP. CMS specifically says that if you’re satisfied your current plan will meet your needs for the following year and it is still being offered, you don’t need to do anything.
But there’s an important difference between choosing to stay after reviewing your coverage and simply doing nothing because you assume nothing changed.
That’s why I recommend an annual review.
And don’t automatically assume your plan will continue to be available. If a plan is leaving Medicare, affected beneficiaries receive notices and need to choose appropriate coverage for the following year.
From My Office: Staying Put Can Be the Right Decision
I want my clients to understand something important:
I don’t consider an AEP review successful only when someone changes plans.
Sometimes we check the doctors, hospitals, prescriptions, pharmacies, copays, premium, maximum out-of-pocket and benefits and determine that the existing plan continues to fit.
Great.
Now we’re staying because we verified the coverage, not because we forgot to review it.
2027 AEP Mistakes I Want You to Avoid
Don’t throw away your ANOC. Medicare says your Annual Notice of Change explains changes in coverage, costs and other plan details that become effective in January. If you don’t receive it, Medicare recommends contacting your plan.
Don’t assume your premium is the only cost that matters. Review deductibles, copays, coinsurance, drug costs and, with Medicare Advantage, the maximum out-of-pocket amount.
Don’t assume your doctors or hospitals are still participating. Provider networks are one of the items CMS specifically notes can change from year to year.
Don’t assume your prescriptions will cost the same. Review your actual medication list against the 2027 formulary and check tiers, restrictions and pharmacy costs.
Don’t choose a plan based primarily on extra benefits. Dental, vision, hearing and OTC benefits may be useful, but they should be considered alongside the medical and prescription coverage you may depend on.
Don’t wait until December 7 to start your research. The 2027 AEP runs from October 15 through December 7, 2026, and elections made during AEP are effective January 1, 2027.
Frequently Asked Questions About the 2027 Medicare AEP
Do I Have to Change My Medicare Plan Every Year?
No.
AEP gives you the opportunity to review and change Medicare Advantage or Part D coverage. If your existing plan continues in 2027 and still meets your needs, you may decide to keep it.
The important thing is to review before you renew.
Can My Medicare Plan Change Even If I Don’t Change Plans?
Yes. Medicare health and prescription drug plans can make changes from one year to the next involving costs, coverage, providers and pharmacies. That’s one reason Medicare tells beneficiaries to review their ANOC and Evidence of Coverage each year.
Can I Change From Medicare Advantage to Another Medicare Advantage Plan During AEP?
Yes. AEP allows Medicare beneficiaries to make permitted Medicare Advantage and Part D enrollment or disenrollment changes for coverage beginning January 1.
Can I Leave Medicare Advantage and Return to Original Medicare During AEP?
Yes. AEP can be used to disenroll from Medicare Advantage and return to Original Medicare.
However, don’t make that decision based on one feature alone. You also need to consider prescription drug coverage and whether you want Medicare Supplement insurance.
Importantly, returning to Original Medicare does not automatically guarantee that you’ll be able to purchase any Medigap policy you want without medical underwriting in every state or circumstance. Medigap enrollment protections depend on factors including where you live and whether you have a guaranteed-issue right.
That’s an area where I strongly recommend understanding the rules before making the change.
Is AEP the Same as the Medicare Advantage Open Enrollment Period?
No.
The Annual Enrollment Period runs October 15–December 7 and is available to Medicare beneficiaries to make permitted Medicare Advantage and Part D changes.
The Medicare Advantage Open Enrollment Period runs January 1–March 31 and has different rules. It’s for people already enrolled in Medicare Advantage and shouldn’t be viewed as a substitute for carefully reviewing your coverage during AEP.
Final Thoughts: Don’t Guess With Your 2027 Medicare Coverage
There are a lot of moving parts to Medicare.
During AEP, you’re potentially comparing premiums, medical copays, maximum out-of-pocket limits, doctors, hospitals, prescription formularies, drug tiers, pharmacies, prior authorization requirements and supplemental benefits.
That’s a lot to research—and overlooking one important detail can potentially become expensive.
You don’t have to do all of that research alone.
As a licensed Medicare agent, I help clients organize the information that matters to them and research their Medicare options based on their individual needs.
Bring me your ANOC, doctors, specialists, hospitals, prescriptions and preferred pharmacy.
Tell me what’s important to you.
Then let’s look at the numbers and coverage together.
Maybe there’s a better option for 2027.
Maybe your existing coverage is still the right fit.
Either way, I want that decision to come from research—not assumptions.
About the Author
Aja Link is a licensed Medicare insurance agent and owner of Aja Link Insurance Services, helping Medicare beneficiaries understand and compare their coverage options.
Aja takes an education-first approach to Medicare. Rather than beginning with a particular insurance plan, she helps clients look at the factors that can have the greatest impact on their coverage and finances—including doctors, specialists, hospitals, prescriptions, pharmacies, healthcare needs and budget.
During Medicare’s Annual Enrollment Period, Aja helps clients review their existing coverage, identify important changes and research available options so they can make an informed decision for the coming year.
Aja Link Insurance Services
Phone: 516-313-8918
Email: ajaglink@gmail.com
Website: ajalinsurance.com
Official Medicare Resources
Medicare Open Enrollment
https://www.cms.gov/priorities/key-initiatives/medicare-open-enrollment-partner-resources
Medicare Annual Notice of Change (ANOC)
https://www.medicare.gov/basics/forms-publications-mailings/mailings/costs-and-coverage/upcoming-plan-changes
Medicare Plan Compare
https://www.medicare.gov/plan-compare/
2027 Medicare Advantage and Part D Information
https://www.cms.gov/newsroom/press-releases/medicare-advantage-medicare-prescription-drug-programs-expected-remain-stable-2027
Medicare & You Handbook
https://www.medicare.gov/publications/10050-medicare-and-you.pdf
Medicare Disclaimer
Aja Link Insurance Services is not connected with or endorsed by the U.S. government or the federal Medicare program. Plan availability, premiums, benefits, provider networks, formularies and cost-sharing can vary by plan and location and may change from year to year. This article is for educational purposes. Review official plan documents and Medicare information when making coverage decisions.